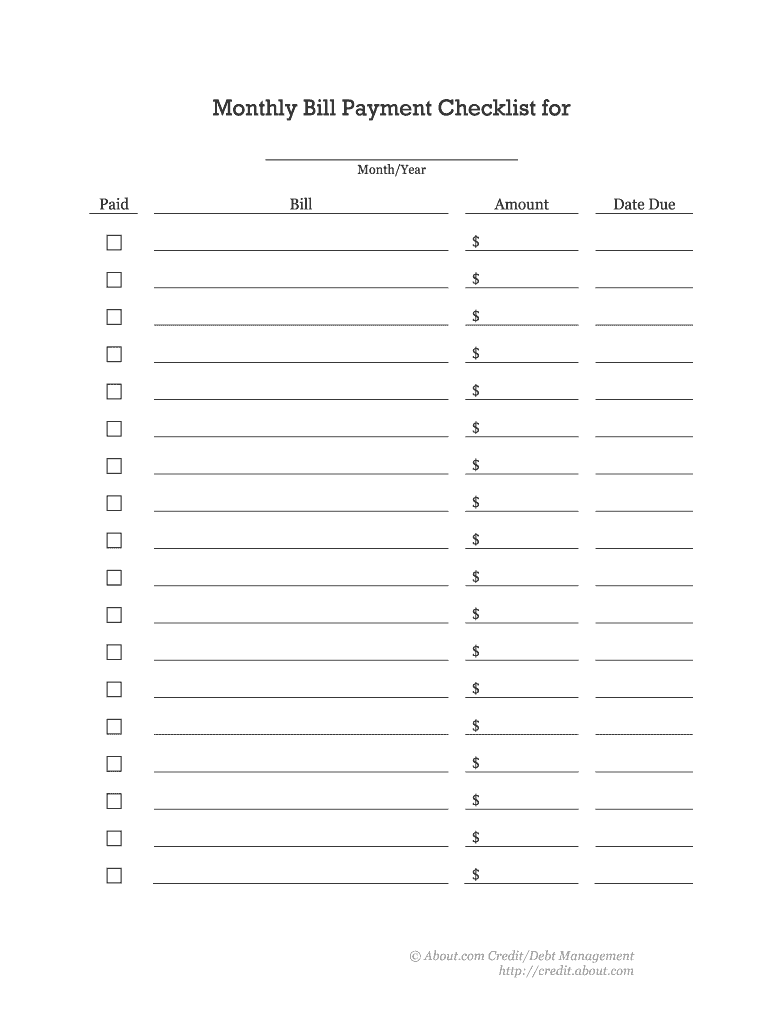
On a rushed morning, I scanned between grading papers and parent emails and stumbled onto pdf free printable monthly bill chart. It promised a quick, tidy way to track dues for our classroom fund and personal bills at a single glance.
Time is rarely generous in my classroom, especially near report cards. I opened the idea with a teacher's pragmatism rather than excitement: would a ready-made sheet really simplify anything, or would I spend more minutes adjusting it than I saved, given our varied student needs today? I appreciated the idea of a clean, printable format, but I wondered how it would fit with our monthly schedule and multiple classes. That moment of hesitation almost kept me from looking again, really today.
First impressions, at a quick classroom glance, in practice
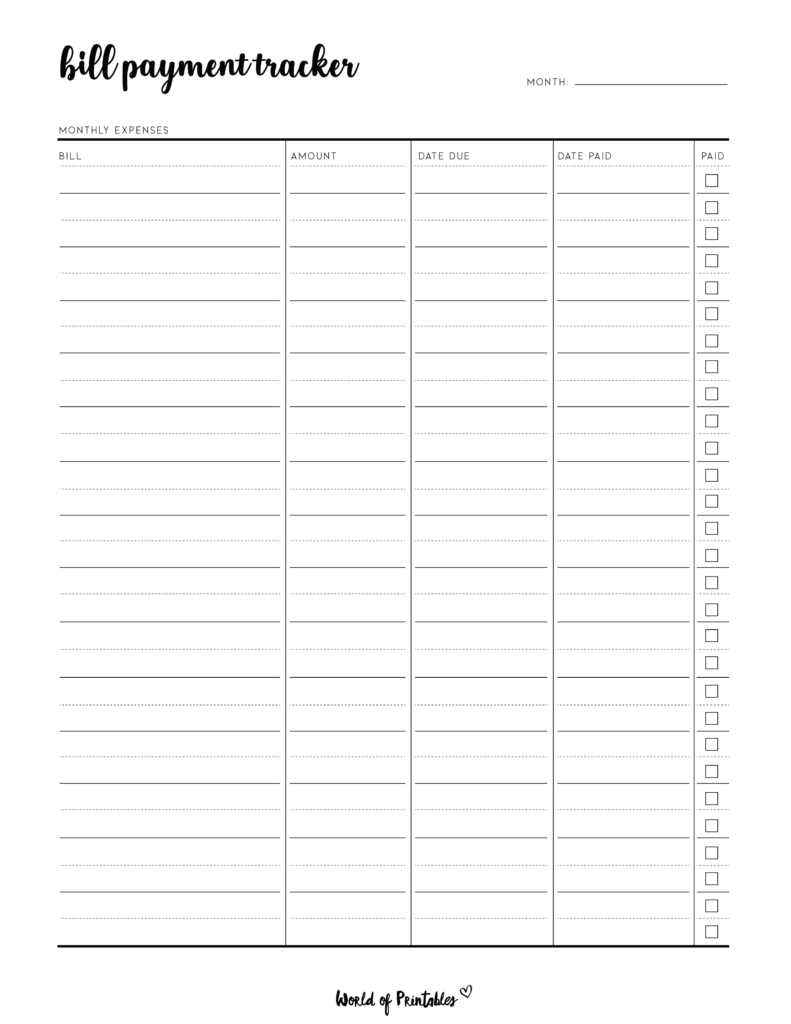
I imagined using it for a weekly budgeting routine with my students: a quick check-in on what we owe for field trips, supplies, and club dues. In practice, I spotted alignment issues on different printers and an ambiguous column that could confuse students. Still, the layout offered a pleasant starting point, something tangible to hand to families. That practical note reminded me to keep expectations modest. In my plan, I would pair this with a class demo for teachers everywhere.
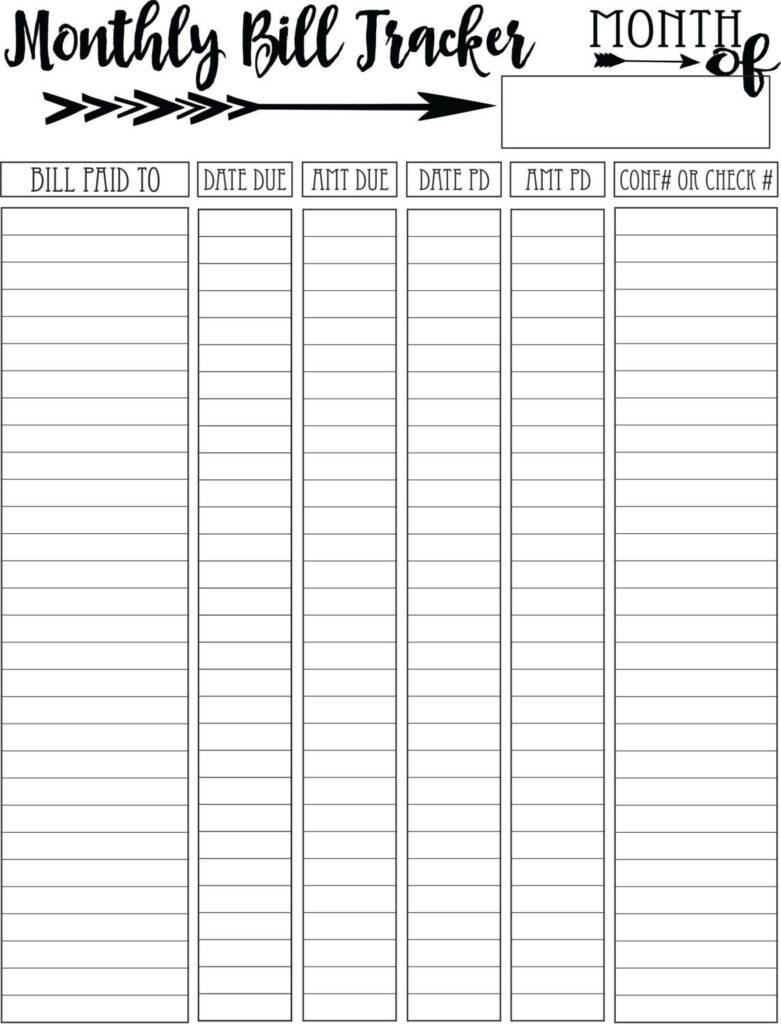
Another tradeoff became clear quickly: a printable like this is great for a snapshot, but it won’t auto-remember categories or totals, and without helpful prompts, families might miss a due date. If I forced the data entry, it would still require my ongoing supervision to stay accurate. I also wished for a flexible date range, something that could stretch beyond a single calendar month. I also wondered about color or themes that might help kids stay engaged during class.
Practical limits in real life for a classroom today
Still, I could see the chart becoming a useful prop during family nights or a quick classroom demo about budgeting. With careful framing, students could compare a bill's due date with our project timeline. The biggest pull remains simplicity; the biggest caveat is that it cannot replace a live ledger or a teacher-made, adaptive tracker. In a real session, we'd test it briefly and then decide what to keep or drop.
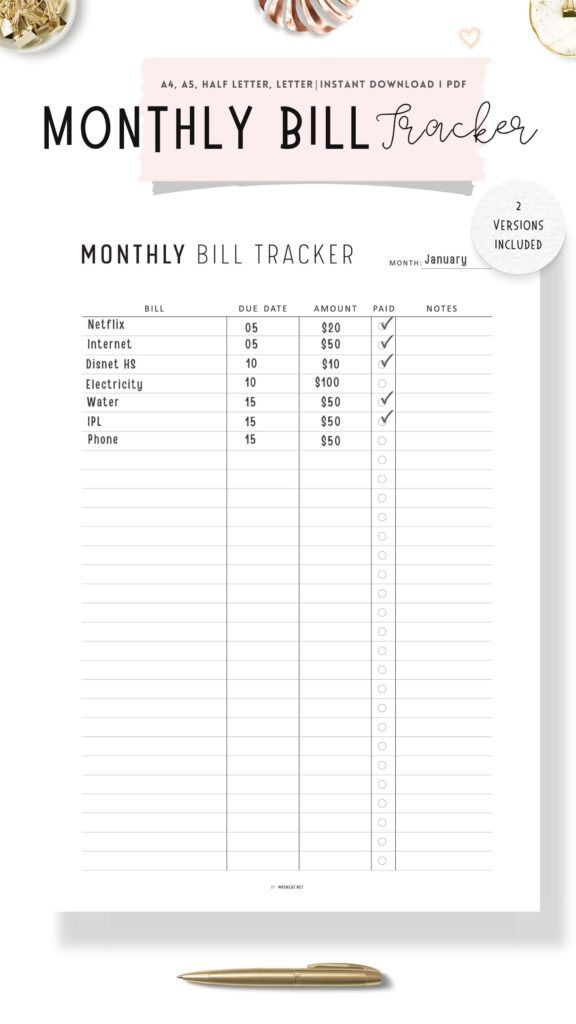
Who benefits, in practice, and why, exactly?
My ideal audience would be a small class, or a PTA treasurer, or a family using the printable as a framework for a home budget. It could be helpful for tracking field-trip payments, monthly dues, or classroom supply orders. It also invites discussion about value, tradeoffs, and prioritization in a real-world context. Used thoughtfully, it could spark practical math conversations as well, making algebraic thinking visible for families in daily life and budgeting discussions.
If I revisited it, I would tweak the typography and add color-coding for categories so the page reads at a glance, perhaps starting with a bold header row and a slightly larger font for due dates. I'd also make the grid more forgiving for printers, ensuring margins stay intact when printed at home. A fillable PDF option would help families, saving me from repetitive copying. A small pilot with a couple of families would help me tune its limits.
So, after a morning of weighing pros and cons, I learned to keep expectations grounded. A simple printable can anchor a plan, but it won't replace careful oversight or ongoing adjustments. It's a helpful prompt to start conversations about money in class and at home, as long as we treat it as a flexible tool, not a miracle cure. If you're curious, try it with modest goals; using pdf free printable monthly bill chart as a starting point.